The Infrastructure Behind Digital Betting. By Chad Beynon
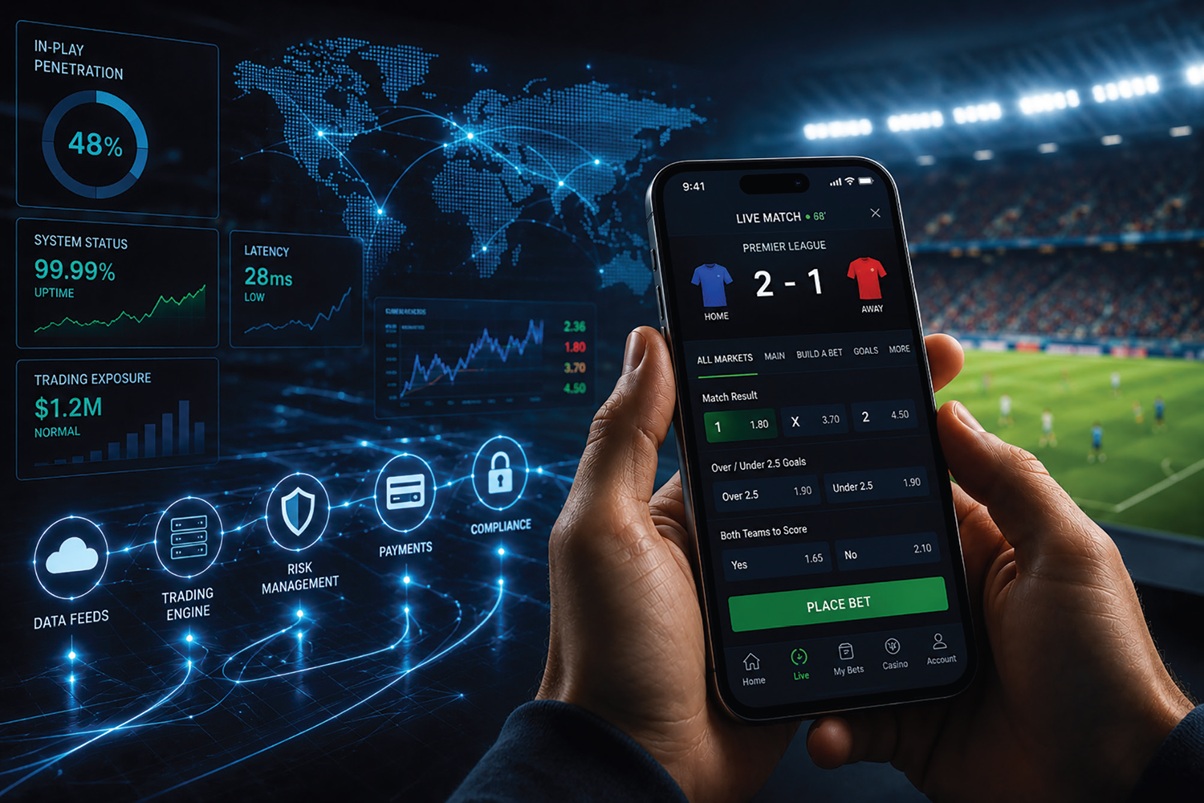
The infrastructure underpinning digital sports betting has evolved into a highly sophisticated, multi-layered ecosystem, and in our view represents a key driver of market share, margin expansion, and long-term competitive advantage across the sector. While the consumer experience is defined by intuitive mobile apps, real-time odds, and immersive features, the economics of the business are increasingly dictated by the strength and ownership of the underlying technology stack—spanning data ingestion, cloud infrastructure, trading systems, payments, and compliance.
Historically, operators relied on a patchwork quilt network of third-party vendors to deliver these capabilities. However, the industry has progressively shifted toward vertical integration, with leading operators investing to internalize key components of the value chain where scale and economics justify it. While this strategy requires significant upfront capital—particularly in data rights, platform development, and trading capabilities—it can drive structurally higher margins over time through cost efficiencies, faster innovation cycles, and greater control over the user experience.
The importance of this infrastructure is most evident in the growth of live, or in-play, betting. In the U.S., in-play penetration has expanded materially in recent years, increasing from roughly ~10% of gross gaming revenue (GGR) to approaching ~50%, driven by both evolving consumer preferences and improvements in platform capabilities. This segment is inherently latency-sensitive, requiring operators to ingest, process, and respond to live sporting events in near real time. Data feeds from official league partners (e.g., Genius Sports, Sportradar), tracking technologies, and aggregators must be continuously validated and disseminated with minimal delay. In addition to in-house improvements has been the general improvement in low-latency speeds, greater network capacity and overall broader reach from 5G. Even marginal delays in updating odds can expose operators to arbitrage opportunities or mispriced markets, with direct implications for profitability. As such, operators have increasingly invested in low-latency architecture, including cloud-native deployments, edge computing, and distributed systems designed for resilience and uptime during peak traffic events (e.g., Super Bowl, FIFA World Cup). From a financial perspective, this creates a higher fixed-cost base but introduces meaningful operating leverage, as incremental volume can be absorbed at relatively low marginal cost.
In parallel, trading and risk management systems represent a core earnings driver. In a live betting environment, operator exposure can shift rapidly as bettors react to game developments. As a result, operators must continuously rebalance their books across thousands of markets, dynamically adjusting pricing to manage liabilities. This is typically achieved through automated trading models that incorporate real-time inputs, historical data, and probabilistic frameworks.
Execution in this function is directly correlated with margin outcomes. Operators with more advanced pricing capabilities can maintain tighter spreads and higher hold percentages, while minimizing volatility in earnings. Conversely, system failures—such as delayed suspensions, inaccurate pricing, or data inconsistencies—can lead to outsized losses, particularly in high-liquidity events. We therefore view investment in proprietary trading technology and quantitative expertise not as a cost center, but as a core revenue-generating capability.
Payments infrastructure is another critical, though underappreciated, lever of both growth and profitability. Real-time betting requires seamless capital movement, with users expecting instantaneous deposits, wager execution, and rapid payouts. Delivering this experience necessitates integration with real-time payments networks, digital wallets, and fraud prevention systems, all while maintaining compliance with jurisdiction-specific regulatory requirements.
While payments introduce incremental costs—primarily via processing fees, fraud mitigation, and compliance overhead—they also drive user engagement and lifetime value. A frictionless payments experience reduces abandonment, increases betting frequency, and enhances customer trust. Additionally, faster settlement cycles can improve operator cash flow dynamics, enabling more efficient capital turnover.
Regulation and compliance further shape the cost structure and operating model. Given the high-frequency nature of in-play betting, regulators impose strict requirements around data integrity, responsible gambling, and transaction monitoring. Operators must deploy systems to detect suspicious behavior, enforce betting limits, and ensure platform integrity. While these capabilities add complexity and cost, they are essential for maintaining licensure and sustaining long-term market access.
From a competitive standpoint, infrastructure ownership is increasingly a key differentiator. Larger, vertically integrated operators that control their data feeds, trading engines, and front-end platforms are better positioned to innovate, optimize pricing, and expand margins. In contrast, smaller or less integrated operators reliant on third-party solutions often face structural margin pressure due to revenue-sharing agreements and reduced flexibility in product development. This dynamic has contributed to continued industry consolidation, as operators seek to internalize strategic assets and build scale advantages. Importantly, many of the most popular user features—such as cash-out functionality, bet builders, and live streaming—are dependent on this underlying infrastructure. For example, cash-out requires continuous recalculation of bet value based on updated odds and exposure, while live streaming integration requires synchronization across multiple real-time data sources. As such, product differentiation at the front end is increasingly a function of backend capability.
Looking forward, we expect continued investment in advanced technologies—including artificial intelligence, machine learning, and edge computing—to further enhance pricing efficiency, personalization, and fraud detection. These innovations have the potential to further widen, the gap between leading and subscale operators.
In summary, while the front-end experience remains critical for customer acquisition, we believe the primary determinants of long-term value creation in sports betting lie within the “hidden backbone” of infrastructure. This includes data systems, trading and risk management, payments, and compliance capabilities. Although capital-intensive, these investments drive operating leverage, margin expansion, and competitive differentiation. At the same time, they introduce financial risk: in a high-speed, real-time environment, errors in pricing, latency, or exposure management can quickly translate into material losses. As a result, infrastructure is not merely a support function—it is central to both profitability and risk in modern digital betting.
 About Chad Beynon
Chad Beynon is Macquarie Capital’s US Head of Research and senior Gaming, Lodging and Theatre analyst. He has followed the sector for over 20 years and collaborates with his global team of gaming analysts. He previously conducted Consumer Research at Prudential Equity Group and is a proud graduate of the University of Maryland.
This original exclusive article was originally published in the June 2026 edition of Sports Betting Operator Magazine Issue 023***